Borrowing capacity isn’t based on your annual turnover—it’s based on your Debt Service Coverage Ratio (DSCR) and Free Cash Flow (FCF).
While most online calculators give a generic figure, UK lenders evaluate strict financial thresholds to determine how much credit your cash flow can comfortably support.
Make SimplyFunded as your preferred source in Google.
1. The Core Calculation: Debt Service Coverage Ratio (DSCR)
UK commercial lenders evaluate affordability using the DSCR. This measures your available operational cash flow against your total debt obligations (existing debt + proposed new debt).
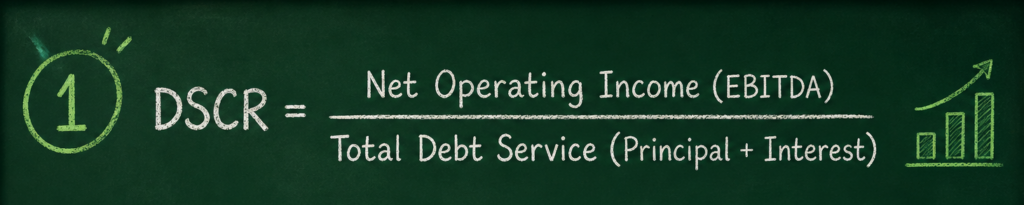
Formula from illustration: DSCR = Net Operating Income (EBITDA) / Total Dept Service (Principal + Interest)
What Lenders Expect:
- DSCR < 1.0x: Automatic rejection. Your cash flow cannot cover repayments.
- DSCR = 1.0x – 1.2x: High risk. Acceptable only with secondary collateral or high-interest short-term facilities.
- DSCR 1.25x: The standard benchmark for tier-1 UK business lenders (High Street banks and institutional debt funds).
2. Real-World Affordability Benchmark
To quickly estimate your maximum monthly loan repayment buffer before applying, use the following formula:
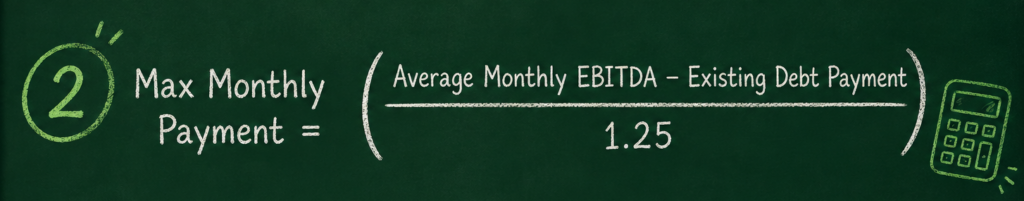
Formula from illustration: Max Monthly Payment = ( Avg. monthly Ebita – Existing dept Payment / 1.25 )
Practical Example
| Financial Metric | Monthly Amount (£) |
| Average Monthly Revenue | £40,000 |
| Operating Expenses (excl. depreciation) | -£28,000 |
| Monthly EBITDA | £12,000 |
| Existing Debt Commitments | -£2,500 |
| Estimated Tax Provision (Corporation Tax/VAT) | -£2,000 |
| Adjusted Net Cash Flow | £7,500 |
Applying the 1.25x Coverage Rule:
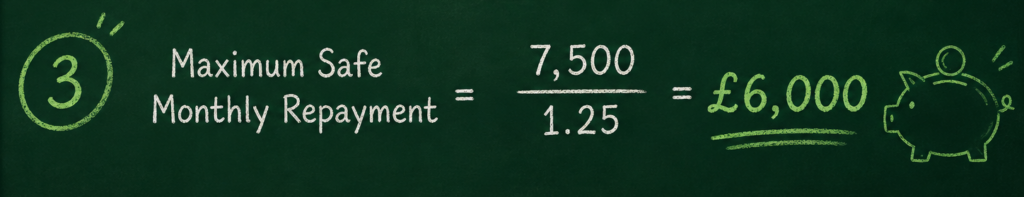
Formula from the illustration: Max Safe Monthly Repayment = 7,500/1.25 = 6,000
Key Takeaway: Even if a broker offers a £10,000/month facility, committing more than £6,000/month leaves your business vulnerable to normal trading dips or late-paying debtors.
3. How Lenders Underwrite UK Businesses
Lenders assess four primary factors during the underwriting process:
| Metric / Stage | Focus Area | Key Checks & Red Flags |
| 1. Bank Statement Stress Testing | Operational Liquidity | • Review 3–6 months of bank activity • Check for un-notified overdraft usage • Identify bounced Direct Debits • Track days with balances under £1,000 |
| 2. Debt Burden Ratio (DBR) | Total Debt Cap | • Calculate Total Debt Cap • Typical lender cap is set between 15%–20% |
| 3. Cash Concentration Risk | Revenue Vulnerability | • Assess reliance on key accounts • Red flag if any single client generates >30% of total revenue |
| 4. Seasonal Fluctuation Adjustment | Downside Resiliency | • Evaluate cash flow across low-revenue periods • Base borrowing limits on the lowest-performing trading quarter |
4. Red Flags That Instantly Kill Affordability
Lenders flag specific bank statement and accounting behaviors during automated open banking reviews:
- High Merchant Cash Advance (MCA) Stacking: Taking multiple short-term daily or weekly debit loans indicates severe working capital distress.
- Persistent Overdraft Utilization: Running at 90%+ of your facility limit signals that your operational cash buffer is depleted.
- Overdue Tax Liabilities (HMRC): Outstanding VAT or Time-to-Pay (TTP) arrangements take priority over unsecured debt repayments.
- Debtor Concentration: Relying on one or two major clients for over 30% of total invoice volume increases revenue vulnerability.
5. Official Regulatory Sources & Citations
To anchor affordability guidance in official UK standards and regulatory frameworks, reference these authoritative authorities:
- British Business Bank (How to Apply for a Business Loan): Recommends pre-application audits of credit reports, cash flow history, and stress-testing repayment capacity across downside trading scenarios.
- Financial Conduct Authority (FCA – Small Business Lending & Personal Guarantees): Outlines regulatory expectations around transparency, unfair enforcement, and liability exposure when personal guarantees are required for commercial loans.
- UK Government / GOV.UK (Late Commercial Payments & Debt Recovery): Frameworks governing statutory interest, debt recovery costs, and business cash-flow protections under UK commercial law.
6. Pre-Application Affordability Checklist
Before submitting an application to a lender or broker:
- [ ] Run an Open Banking audit: Ensure there are no bounced payments or un-notified overdraft charges in the past 90 days.
- [ ] Calculate your trailing 12-month EBITDA: Exclude one-off capital injections or non-operational revenue.
- [ ] Establish your DSCR: Verify that your projected post-loan coverage ratio stays above 1.25x.
- [ ] Prepare a downside scenario: Stress-test your cash flow against a 15–20% reduction in monthly revenue.